Who is Southern Loan Servicing?
Creative financing specialists since 1985 — from Louisiana Bond for Deed to every owner-financed structure in the book.
Southern Loan Servicing has spent 41 years doing one thing and doing it well: servicing the owner-financed and creatively-structured real estate loans that banks and big servicing shops won't touch. Bond for Deed. Wrap-around mortgages. Subject-to acquisitions. Lease options and rent-to-own. Private notes and hybrid seller-financed structures. If the deal doesn't fit inside a Fannie Mae box, it fits inside our practice.
We are the right size for this work. Large enough to run reliable operations — automated payments, escrow for taxes and insurance, IRS reporting, 24/7 online account access, disciplined recordkeeping. Small enough to say yes to the unusual deal, get on the phone with a borrower or seller, and actually understand what's in front of us. That combination is rare in loan servicing, and it's where our clients keep telling us the value shows up.
We serve buyers, sellers, note brokers, loan brokers, and private investors across the country. Flat monthly fee, no hidden charges, same fee whether the note is $30,000 or $3 million. Whether you are a first-time seller carrying paper on your family home or an investor running a portfolio of wrap deals, you get the same rigor and the same attention.
Where We Came From
We opened our doors in 1985 as Southern Escrow & Title, Inc., built around a peculiar Louisiana product called the Bond for Deed. Louisiana never fully abandoned the civil-law tradition, and the BFD is a piece of that heritage — a seller-financed contract where the buyer takes possession and pays monthly, but the seller keeps legal title until the contract is paid in full. It fills the gap for buyers who can't qualify for a bank mortgage and for sellers who want steady monthly income instead of a lump-sum sale.
The catch is that BFDs are genuinely hard to service correctly. They require escrowed collection with a licensed third party, real-time tax and insurance escrow, careful IRS reporting, tight recordkeeping in case of dispute, and airtight protocols for handling default — because unwinding a Louisiana BFD is not the same as foreclosing a mortgage. Most title companies and general-purpose servicers won't take them on. Louisiana required a specialist, so we became one.
We hold the first Bond for Deed servicing license the Louisiana Office of Financial Institutions ever issued, and over four decades we've serviced more BFD and owner-financed contracts than any other firm in the state. In 2016 we renamed to Southern Loan Servicing to reflect what the practice had already become — a firm that services every kind of owner-financed and creative loan, not just Louisiana BFDs.
The expansion followed the deals. Real estate investors began bringing us subject-to acquisitions, then wrap-around mortgages, then lease options and rent-to-own contracts, then hybrid structures that combine two or three of the above, then private-money and hard-money notes secured by non-traditional collateral. The muscles we'd built on BFDs — escrow discipline, tax reporting, party-to-party neutrality, handling the awkward edge cases — turned out to be exactly the muscles the rest of creative financing needed.
Why a Specialist
Loan servicing sorts itself into three buckets, and creative financing gets underserved by two of them.
The big shops won't touch it. National servicers are built for high-volume, cookie-cutter conforming loans. A wrap-around mortgage with an underlying lien, or a subject-to deal with a due-on-sale exposure, or a BFD with escrow for two different tax authorities and a rider on the insurance — those are exceptions to their systems, not use cases. Their staff aren't trained on the structures. Their software can't model the payment splits. They decline the business.
The small shops don't do enough of it. A mom-and-pop servicer might handle a handful of owner-financed notes, but they haven't built the operational spine — the escrow controls, the audit trail, the IRS reporting cadence, the default protocols, the systems for coordinating multiple parties on one contract. When something unusual comes up, they're figuring it out for the first time.
We sit in the middle. Large enough to have built real infrastructure — modern software, formal audit trails, staff who have seen thousands of these deals and can recognize the pattern instantly. Small enough to actually pick up the phone, evaluate a novel structure on its merits, and adapt when a deal doesn't match anything we've done before. That's the sweet spot, and it's where creative financing needs a servicer to live.
The result: if you bring us a creative financing deal, we've probably serviced something like it before. And if we haven't, we'll figure it out with you — because that's the practice we've been running for 41 years.
Where We Work
Louisiana is home. We're licensed by the Louisiana Office of Financial Institutions, we service more Bond for Deed contracts than anyone in the state, and we know Louisiana's civil-law quirks cold. But creative financing is a national practice, and so is ours.
We service owner-financed notes and creative structures across the country — Bond for Deed in Louisiana, Contract for Deed and Land Contract in the Midwest and West, wrap-around mortgages and subject-to acquisitions in every state that permits them, lease-option and rent-to-own contracts wherever an investor is running that play. The mechanics change from state to state; the servicing discipline doesn't.
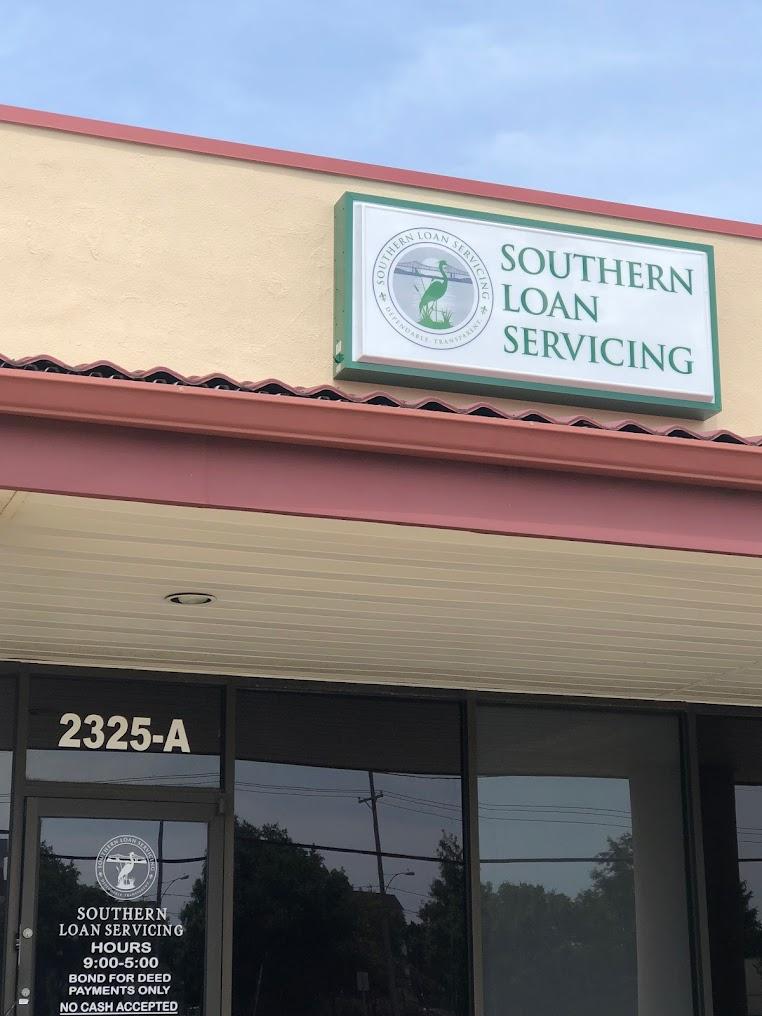
If you are planning to buy a home using owner-financing, you can find us just outside of New Orleans at:
2325 Manhattan Boulevard, Harvey, LA 70058
The Team
Every person on our staff is trained on the full creative-financing menu — not just how a Bond for Deed works, but how a wrap unwinds when the underlying gets called, what a subject-to seller needs to hear about credit-reporting risk, how to structure escrow when a note has a balloon in year seven. We hire for that judgment and we invest in keeping it sharp.
When you call us, you get a human who understands your deal — not a call-center script and not a form you fill out and wait on. If you have a creative financing note that needs a servicer, or a deal you're structuring and want to talk through, we'd like to hear about it.